Mortgage rates jumped to their highest level in almost three years this week, and if you're shopping for a home in Cherry Hill, Moorestown, Mount Laurel or anywhere else in South Jersey, you've probably felt it. I'm Jerry Mac, and after 23 years helping buyers and sellers across this area, I can tell you this: a scary headline doesn't have to derail your plans. It does mean you need a smarter strategy.
Here's what happened, what it does to your monthly payment, and what I'd actually do if I were buying right now.
What happened to mortgage rates this week
The average 30-year fixed mortgage rate rose to 7.28% this week, up from 7.03% the week before, according to Freddie Mac data reported by Fox Business. That's the highest level since November 2023. A year ago, the same rate was 6.34%.
The cause isn't one single event. NerdWallet points to a mix of stubborn inflation, jittery bond markets and uncertainty about what the Federal Reserve does next. The 10-year Treasury yield, which mortgage rates tend to follow, has been climbing too.
One note: daily lender quotes run a bit higher than Freddie Mac's weekly average, and your own rate will depend on your credit score, down payment and loan type. Rates change daily, so treat these numbers as a snapshot from early October 2026.
What a 7% rate does to your monthly payment
On a $450,000 home with 20% down, moving from last year's rate to today's adds about $225 a month, or roughly $2,700 a year. Here is the principal and interest on a $360,000, 30-year fixed loan:
| Rate | When | Monthly principal and interest |
|---|---|---|
| 5.90% | February 2026 low | $2,135 |
| 6.34% | One year ago | $2,238 |
| 7.28% | This week | $2,463 |
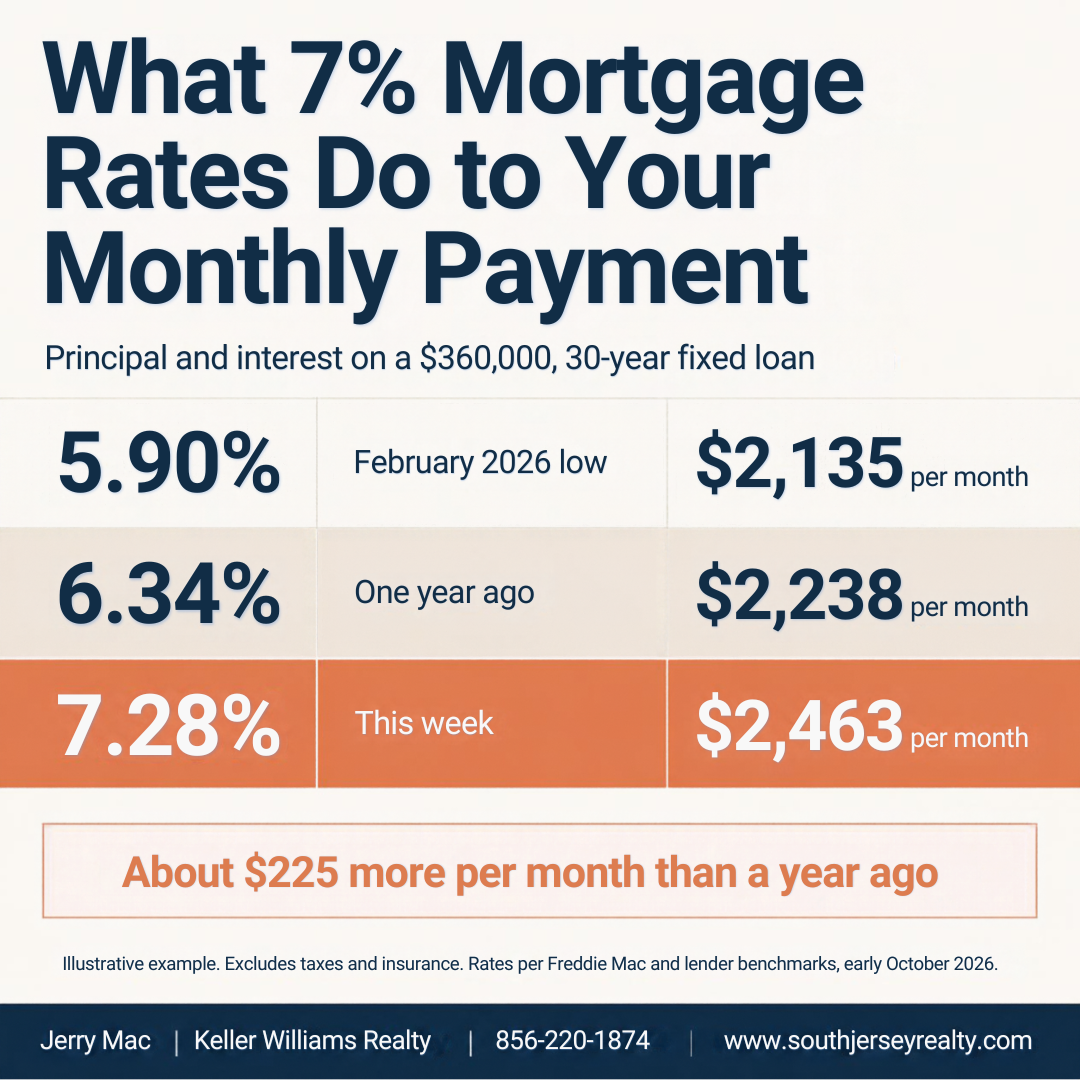
These figures are illustrative and don't include property taxes, homeowners insurance or any mortgage insurance. New Jersey property taxes can be a big part of the monthly cost, so ask for a full payment estimate before you fall in love with a house. The $450,000 price is only an example, not a quote for any specific town.
Should you wait to buy?
It depends on your situation, and nobody, me included, can reliably predict where rates go next. Here is how I weigh it with buyers.
Reasons to wait:
- Your budget is already tight and a higher payment would stretch you too far.
- You plan to move within a few years, so you won't have long to benefit from the home.
- You need more time to build savings or improve your credit score.
Reasons not to wait:
- You've found a home that fits your life, and waiting means competing with other buyers if rates fall.
- You can afford today's payment comfortably.
- You may be able to refinance if rates drop, though refinancing has closing costs and isn't guaranteed.
The key point: you can change your rate later by refinancing, but you can't change your purchase price after closing. That's why a good price and good terms on the home matter just as much as the rate.
Smart ways to buy in a higher-rate market
High rates make strategy matter more. These are the options I walk buyers through:
- Negotiate seller concessions. Some sellers will contribute toward closing costs or a rate buydown, especially if a home has been on the market a while.
- Look at a rate buydown. Paying points, or having the seller pay them, can lower your rate. Ask your lender how long it takes to break even.
- Compare loan types. FHA, VA and adjustable-rate mortgages can come in below a conventional 30-year rate. A 5/1 adjustable-rate loan, for example, was quoted around 6.6% to 6.8% in early October, but your rate can change later, so it only fits some buyers.
- Shop more than one lender. Rate quotes vary, and getting several in one week can show you real differences.
- Strengthen your credit before you apply. Even a small bump in your score can change the rate you're offered.
- Get pre-approved first. You'll know your real budget and can move fast when the right home comes up.
I work with a trusted mortgage partner I'm happy to introduce you to for a no-pressure pre-approval conversation.
Why local experience matters right now
National rate headlines don't tell you what's happening on your street. Every South Jersey town moves differently, from Cherry Hill and Voorhees to Moorestown, Mount Laurel, Marlton, Cinnaminson and Maple Shade. Pricing, inventory and seller flexibility vary by neighborhood and even by month.
I've worked through many rate cycles in 23 years, including the high-rate years, and I've seen buyers do well in all of them by staying calm, negotiating well and picking the right home. I'm licensed in both New Jersey and Pennsylvania, so if your search crosses the river, I can help with that too.
Frequently asked questions
What are mortgage rates right now?
The Freddie Mac weekly average for a 30-year fixed loan was 7.28% in the first week of October 2026, the highest since November 2023. Individual lender quotes vary.
Will mortgage rates go down soon?
No one can say for sure. Rates follow the bond market, inflation and Federal Reserve expectations, and they can move in either direction from week to week.
Should I buy a house now or wait for lower rates?
If you can afford the payment comfortably and found a home you love, buying now can make sense. If a higher payment would strain your budget, waiting while you save may be wiser.
How much does a higher rate cost me per month?
On a $360,000 loan, going from 6.34% to 7.28% adds about $225 a month in principal and interest. The exact amount depends on your loan size.
Can I refinance later?
Often yes, if rates fall and your finances allow, but refinancing has closing costs and no guarantee. Buy a home you can afford at today's rate.
Do you help buyers in Pennsylvania too?
Yes, I'm licensed in both New Jersey and Pennsylvania.
Thinking about buying in South Jersey?
If you want a straight answer about what you can afford and what makes sense in today's market, let's talk. I'll walk you through your numbers, introduce you to a trusted lender for pre-approval, and help you find the right home in Cherry Hill, Moorestown, Mount Laurel, Voorhees, Marlton, Cinnaminson, Maple Shade, Palmyra, Medford, Collingswood or beyond.
Jerry Mac, Keller Williams Realty
Call or text: 856-220-1874
Website: www.southjerseyrealty.com
Sources
- Fox Business: Mortgage rates surge to highest level since 2023 (Freddie Mac weekly data, October 1, 2026)
- NerdWallet: Mortgage rates today, Thursday, October 1
- LendingTree: Current mortgage rates, October 2026
- The Mortgage Reports: Mortgage rates today, October 2, 2026
Payment figures are my own calculations on a $360,000, 30-year fixed loan, principal and interest only. The February 2026 low of 5.90% comes from a daily lender benchmark reported by Mortgage Daily, which is measured differently from Freddie Mac's weekly average.